With years of providing specialist horse insurance behind us, we understand the importance of keeping your horse healthy, happy and safe. Unfortunately, animals don’t have access to the kind of health care that we do, and vet’s fees can soon add up. In 2025 our average horse insurance claim for digestive issues was £905, the most common claim being for Gastric Ulcers.
We’re all very aware of the rising cost of living at the moment; coupled with rising hay prices and bedding costs that are being passed on to the consumer and the average price of livery increasing, the overall cost of horse ownership is getting more expensive. We all tend to think that the worst won’t happen, but factoring in the unexpected is a huge part of owning any animal, particularly one that’s as big, and sometimes unpredictable, as a horse can be.
But what if you have an unexpected vet’s fee? What if your horse gets a serious health condition, or needs surgery? What if it damages someone else’s property, or is stolen? This is where horse insurance comes in as it could help protect against unexpected costs. Insurance can also be confusing; what does excess mean? And what kind of things can you claim for?
With this in mind, we’ve put together a guide to horse insurance.
WHY SHOULD I CONSIDER HORSE INSURANCE?
Anyone involved in the equine industry, whether that’s as an owner, a trainer, rider or breeder, knows that horses can bring a lot of pleasure, but they’re not the cheapest animal to own. Apart from the initial cost of buying one, you also have to factor in livery costs, feed, forage and bedding, as well as general maintenance such as checking their hooves and teeth and keeping on top of their worming programme. On top of this you have to take into account the costs involved if your horse goes missing, gets stolen, or if you have an accident.
HOW MUCH COULD I EXPECT TO SPEND ON VET’S FEES FOR MY HORSE?
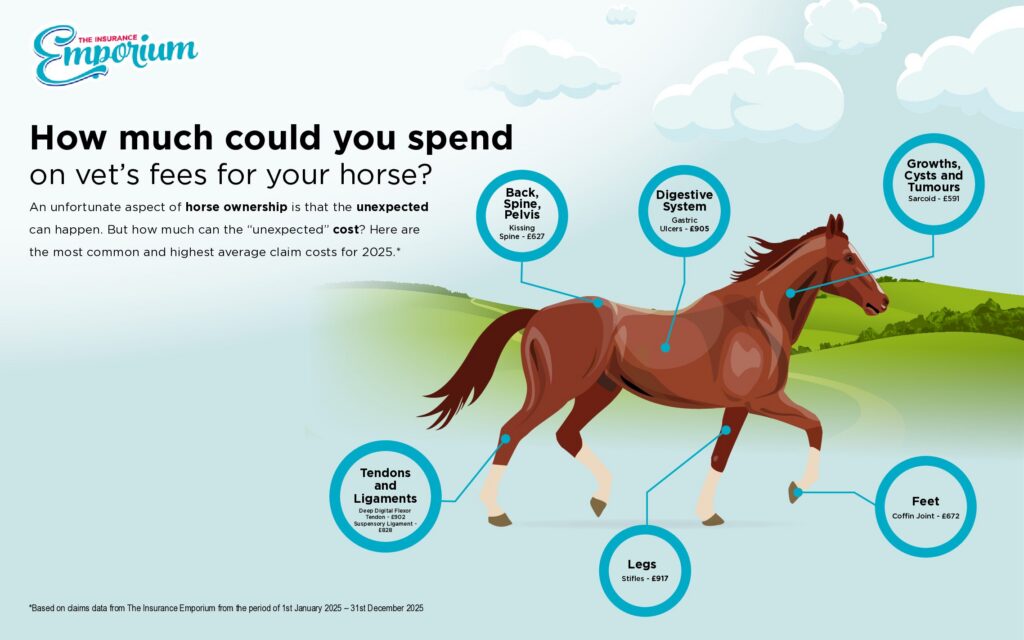
We’ve put together some data* on the most common claims alongside the most expensive claims, to give a rough idea of how much vet’s fees can be for unexpected illnesses and injuries.
Back, Spine, Pelvis
- Average claim value – £637
- Highest average claims value and most common claim – Kissing Spine – £627
Digestive System
- Average claim value – £933
- Highest average claims value and most common claim – Gastric Ulcers – £905
Growths, Cysts, Tumours
- Average claim value – £686
- Highest average claims value and most common claim – Sarcoid – £591
Tendons and Ligaments
- Average claim value – £762
- Highest average claims value – Deep Digital Flexor Tendon – £902
- Most common claim – Suspensory Ligament – £828
Legs
- Average claim value – £787
- Highest average claims value and most common claim – Stifles – £917
Feet
- Average claim value – £584
- Highest average claims value and most common claim – Coffin Joint, Distal Interphalangeal Joint – £672
Bone Disease
- Average claim value – £686
- Highest average claims value and most common claim – Hock Arthritis – £656
Laminitis
- Average claim value – £475

WHAT DOES HORSE INSURANCE COVER?
Horse insurance generally includes a ‘Standard Benefit’, as well as a selection of ‘Optional Benefits’ that you can choose from, for a tailored policy to suit your unique needs. At The Insurance Emporium, our equine insurance policies for horses under 20 years old come with ‘Death, Theft or Straying’ as standard. This is if the horse dies or is put to sleep following emergency or non-emergency euthanasia or is not found within 90 days of straying or being stolen from the stabling address.
Then you can choose from the following optional benefits:
- Vet’s Fees – The cost of treatment and/or complementary therapy where the horse suffers a veterinary incident.
- Complementary Treatment – This must be carried out by your vet or a qualified practitioner (who is a member of a recognised association) recommended by your vet.
- Referral Vet Transportation & Livery – Transportation and livery costs whilst the horse is treated by a referral vet.
- Disposal Costs – The cost of removal and disposal of the horse’s body following its death.
- Saddlery & Tack – Where your saddlery and tack are stolen or accidentally damaged whilst you are taking part in or preparing for an activity specified in your type of use.
- Loss of Use (Permanent incapacity) – Where your horse is completely or partially permanently incapacitated from carrying out the functions for which it was vetted and insured.
- Public Liability – Your legal liability to others for damages and costs arising out of the ownership or use of your horse.
- Personal Accident – Death, total permanent disablement, loss of hearing, loss of sight, or loss of limbs as a direct result of a bodily injury sustained whilst riding, handling, caring for, or interacting with the horse.
- Dental Treatment – Dental treatment following an accidental bodily injury to your mouth and/ or teeth whilst riding, handling, caring for, or interacting with the horse.
WHAT DIFFERENT TYPES OF COVER ARE AVAILABLE?
At The Insurance Emporium we offer two different payment options depending on the type of cover you want, these are:
- Lunar Monthly – this runs in periods of 28 days; cover renews each 28 days as long as the premium is paid.
- Yearly – this is payable annually and cover renews annually.
WHAT DO I NEED TO CONSIDER WHEN TAKING OUT HORSE INSURANCE?
The value of your horse could be affected by:
- Their age.
- Their health.
- Their breed.
- The type of equestrian activities you intend to use your horse for.
You should always check the policy wording so you know exactly what you’re covered for; there may also be general exclusions such as certain treatments and pre-existing conditions that may not be covered. You need to inform your insurance company as soon as possible if there are any changes to your circumstances that could affect your policy, and it’s your responsibility to make sure your horse is microchipped, regularly wormed, and vaccinated.

FREQUENTLY ASKED QUESTIONS
Does horse insurance cover injuries from rider accidents?
Yes, with the Personal Accident optional benefit you’re covered if you sustain an accidental bodily injury as a result of riding, handling, caring for, or interacting with your horse and that injury results in death, loss of hearing, sight or limbs or renders you totally permanently disabled for a consecutive period of 365 days.
Does a horse trailer need insurance?
You’re not legally obliged to have horse trailer insurance but towing a trailer does come with risks so taking out cover could be a good idea, particularly if you attend horse shows/events, buy or sell horses, own stables or train horses. You can also get insurance for if you hire a horse trailer.
Can I get horse insurance for pre-existing conditions?
No, you won’t be covered for pre-existing conditions, meaning injuries or illnesses that existed before your policy started.
Are racehorses and competition horses insured by standard horse insurance?
We do not insure racehorses, however our horse policy covers several equestrian activities if you compete. Just make sure you select the appropriate type of equestrian activities when going through the quotation.
Can I get veteran horse insurance?
Yes, veteran horse insurance covers horses 20 years and over but has different standard, and optional, benefits, so remember to check your policy wording.
Do horses need insurance on the road?
While there’s no legal requirement to have insurance when riding on the road, most responsible riders have insurance that includes public liability.
Do horse riders need insurance?
If you don’t own a horse, but ride one, a Horse Rider Only policy will provide cover for you, and some emergency cover for the horse, e.g. emergency vet fees.
What’s the maximum value that you can insure a horse?
This figure may differ between insurance companies. At The Insurance Emporium, a horse can be insured with us for up to £15,000 for a horse under 20 years old, £2,000 for a veteran horse.
What if my horse is ridden by someone else?
Our horse or veteran horse policies cover anyone, aged five to 75 years, who is riding, leading, handling or caring for your horse with your permission if you have selected Public Liability cover as an optional benefit.
What does excess mean?
An excess is the part you pay towards a claim. With our horse insurance policies, there’s no excess to pay on our Standard Benefit, but there are three Optional Benefits where you need to pay an excess: Vet’s Fees, Saddlery & Tack and Public Liability (Standard) so check your policy schedule.
What does loss of use mean?
There are two types of loss of use; Complete – where your horse cannot undertake any functions for which it was vetted and insured, and it is put to sleep and Partial – where your horse cannot undertake any functions for which it was vetted and insured but can undertake other equestrian activities, or you choose to breed or retire them.
Are there any conditions for keeping my saddlery and tack safe?
Yes, when not in use you need to adhere to security requirements, otherwise your insurance may be invalid, and your claim may be rejected.
Can I insure more than one horse?
Yes, you can insure more than one horse, and you will be eligible for a multi-horse discount. At The Insurance Emporium, if you insure more than one horse, you will be eligible for an extra 10% discount on each of your horse insurance policies. The multi-horse discount is either applied at inception of any new horse policies or at renewal of existing horse policies.
Having horse insurance in place means that if you are faced with an unexpected bill for an **injury, illness, accident then you know you have the cover you need, as our policies are flexible, with the option to tweak them. So, give us a call or visit our website for further info and to get a free, no-strings quote today.
Watch Our Customer Testimonial
*Claims data presented is from The Insurance Emporium’s equine claims between 01.01.2025 – 01.12.2025. The methodology behind the highest average claims value was achieved where there were 100 or more claims for a condition.
**Different benefits apply to veteran horse insurance policies, please check the product information and policy wording.
All content provided on this blog is for informational purposes only. We make no representations as to the accuracy or completeness of any information on this site or found by following any link on this site. We will not be liable for any errors or omissions in this information nor for the availability of this information. We will not be liable for any loss, injury, or damage arising from the display or use of this information. This policy is subject to change at any time.
We offer a variety of cover levels, so please check the policy cover suits your needs before purchasing. For your protection, please ensure you read the Insurance Product Information Document (IPID) and policy wording, for information on policy exclusions and limitations.